Secure Wegovy Online: Compare Local Prices and Find Best Deals
How to Use Wegovy and What to Expect
Think of your Wegovy treatment like training for a long-distance race. You wouldn’t try to run twenty miles on your first day without feeling the burn. Because of this, the protocol utilizes a gradual titration method to let your system acclimate to semaglutide.
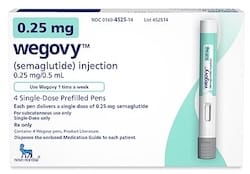
Initially, you will likely start at a baseline of 0.25 mg once every seven days. This opening chapter isn’t designed for rapid body transformations. Instead, it serves as a gentle introduction for your gut, helping to dodge the stomach troubles that often cause people to throw in the towel.
As you settle into the routine, your medical professional will incrementally boost your dosage. You will typically transition through 0.5 mg, 1.0 mg, and then 1.7 mg levels. Each jump is a deliberate step to keep your metabolism steady while chasing those clinical milestones.
Consistency acts as the glue holding your progress together. If you skip a scheduled shot, it feels like pedaling a bike uphill; regaining that lost momentum takes extra effort. Your next steps depend entirely on how many days have slipped by since your last injection.
Injection Protocols and Weekly Rhythm
Consistency is the name of the game when managing a weekly medication. Many users find success by designating a fixed “injection day”—perhaps every Sunday—to turn the task into a mindless habit. It becomes as easy as a morning cup of coffee once it is part of your routine.
You will administer the medication via a subcutaneous shot, targeting the fatty layer right under your skin. You have three primary zones to choose from: your thigh, your abdomen, or the back of the arm. Most people find the stomach area to be the most convenient spot.
The delivery pen is surprisingly simple, behaving much like a standard ballpoint pen. You merely click, dose, and wait. It is a momentary task that won’t derail your afternoon, though you must be precise to avoid wasting any of the costly liquid.
If stomach upset becomes a nuisance, try shifting your target site every week. It is much like walking in a different pattern to avoid a worn-down path. Moving the injection site can prevent skin irritation and help soothe localized soreness.
Financial Planning and Real-World Costs
We should address the elephant in the room: the price tag. Wegovy is a high-end pharmaceutical, and it comes with a high-end cost. Depending on your local area and your specific insurance policy, the monthly expense can feel like a heavy blow to your wallet.
Monthly expenses fluctuate significantly between households. For those without robust insurance, you might find yourself paying anywhere from $1,200 to $1,500 every month. Because it is such a large investment, it is wise to ask your doctor about patient assistance programs to ease the burden.
To help you prepare for the financial commitment, look over these common monthly cost estimates:
| Insurance Type | Expected Monthly Total | Typical Patient Share |
| Comprehensive Coverage | $25 – $50 | Co-pay only |
| Limited Coverage | $300 – $600 | Co-insurance/Deductible |
| No Coverage | $1,300+ | Full retail price |
Keep in mind that these figures are just rough benchmarks. Your actual bill is dictated by your deductible and the specific contracts held by your local pharmacy. Always get the facts from your insurance carrier before you begin so you aren’t blindsided at the checkout counter.
Financial Realities of Purchasing Wegovy in the US
Attempting to budget for weight-loss prescriptions can feel like trying to catch smoke with your bare hands. The financial landscape is rarely a straight line from point A to point B. You might prepare for a simple transaction at the counter, only to collide with a wall of deductibles and complicated authorization requirements.
Let’s be blunt: Wegovy is far from a cheap, everyday commodity. It is a high-demand, specialized drug. Because interest in GLP-1 treatments has reached a fever pitch, the market has shifted. The price tag you see on a website might look nothing like the actual charge on your bank statement.
Staying ahead of these price swings requires a bit of detective work. Many users discover that their monthly out-of-pocket expense changes depending on their pharmacy choice or whether they use a specialty provider. It is a moving target, and being proactive is the only way to prevent your bank account from feeling the sting.
What Determines Your Total Bill?
First, you must dig into your insurance company’s specific drug formulary. Every provider treats Wegovy differently. Some companies classify it as a vital medical necessity, while others slap it under “weight management” labels, which usually come with much harsher restrictions. It is the difference between a smooth highway and a rocky, uphill climb.
Your deductible is the primary engine behind sudden “sticker shock.” If you haven’t reached your annual limit yet, you might be footing the entire retail bill for several months. Once you hit that magic number, the financial landscape changes overnight. It is a game of endurance that requires a thick skin.
Where you pick up your script also matters. A massive retail pharmacy chain might have different negotiated rates than a small local shop or a mail-order service. It is worth acting like a savvy shopper by calling several different outlets to see where the price settles most comfortably for your wallet.
Keep an eye out for help from the drug maker. Many pharmaceutical firms offer assistance programs that serve as a financial lifeline for those struggling with high costs. These vouchers can often bridge the gap between what your insurance covers and the actual amount you can afford to pay.
The data below illustrates how various levels of coverage might impact what you spend every month:
| Coverage Category | Estimated Monthly Expense | Main Cost Factor |
| Full Coverage | $25 – $75 | Fixed co-pay |
| Tiered/Limited Coverage | $300 – $600 | Co-insurance & deductible |
| No Insurance (Self-Pay) | $1,300+ | Full retail pricing |
| Manufacturer Discount Plan | $250 – $500 | Discounted retail rate |
Navigating the Insurance Maze
If your claims keep getting rejected, don’t throw in the towel quite yet. Often, the “Prior Authorization” (PA) acts as the gatekeeper between you and your medicine. Your physician’s office will likely need to prove that you have previously attempted other lifestyle interventions or weight loss strategies.
Think of the PA requirement as a legal argument for your health. The more substantial documentation your doctor provides regarding medical necessity, the higher your chances of success. It can be a frustrating cycle of paperwork, but it is frequently the most effective way to bring your monthly costs down to earth.
It is also worth investigating if your employer provides any specific wellness perks. Certain modern health plans offer assistance for weight loss that operates separately from standard medical coverage. These benefits can sometimes bypass the usual red tape and offer a much smoother path for employees.
Finally, make it a habit to save every “Explanation of Benefits” (EOB) you receive in the mail. When dealing with such expensive prescriptions, clerical errors are bound to happen. Keeping a thorough paper trail ensures that if a claim is processed wrong, you have the evidence needed to fix it.